Why High MRR Growth Masks a Churn Problem
A SaaS company can post 40% year-over-year MRR growth and still be losing customers faster than it can replace them. This happens more often than founders admit. The math of compounding new sales can
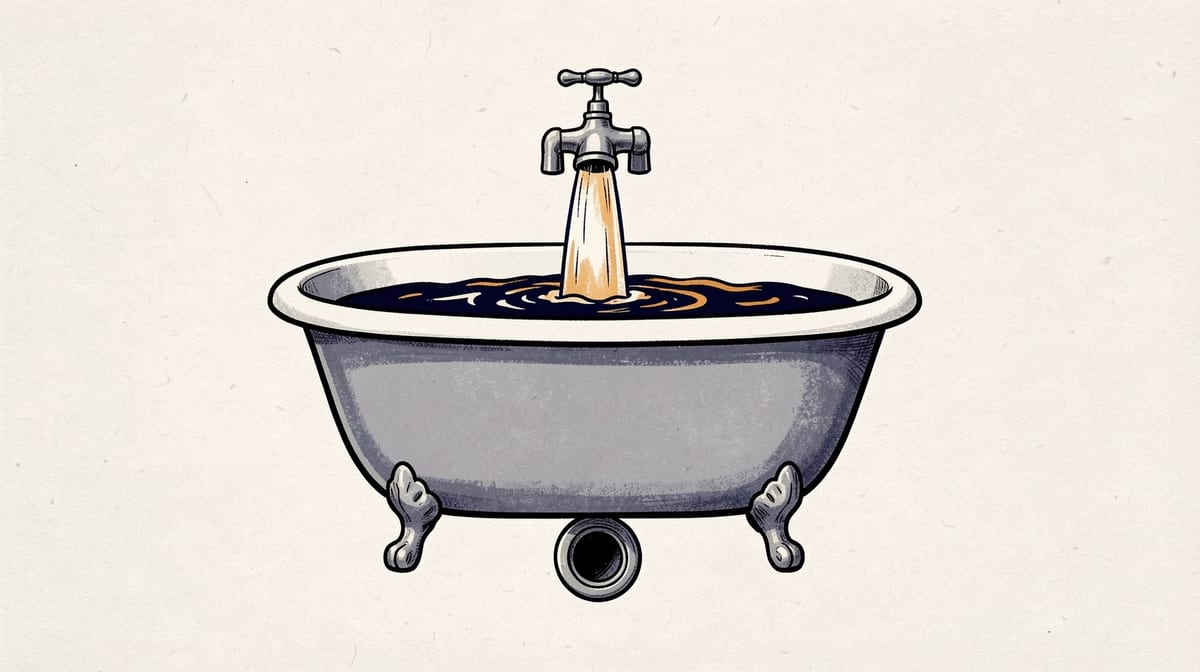
A SaaS company can post 40% year-over-year MRR growth and still be losing customers faster than it can replace them. This happens more often than founders admit. The math of compounding new sales can bury a churn problem for a year or more before it shows up on the top line.
That is the trap. Monthly recurring revenue measures money coming in the door this month. It says nothing about whether the customers who paid last month are still around, still happy, or quietly building a case to cancel. Understanding the real MRR churn relationship in SaaS metrics is the difference between a business that compounds and one that runs in place.
This piece breaks down how expansion revenue and new sales hide retention problems, why investors have shifted their attention to net revenue retention, and what founders should track instead of watching the top-line number climb.
The MRR Growth Illusion
Picture two companies, both growing MRR by $50,000 a month. Company A adds $80,000 in new sales and loses $30,000 to churn and downgrades. Company B adds $55,000 in new sales and loses only $5,000. Both hit the same growth number this month.
Only one of these businesses is healthy. Company A needs to keep finding bigger and bigger sales numbers just to stay flat, because its customer base is leaking. Company B can slow down its sales engine and still grow, because its existing customers stick around.
This is the core problem with using MRR growth rate alone as a health check. It nets out acquisition and attrition into one number, so a business bleeding customers looks identical to a business retaining them, as long as new sales are large enough to cover the hole.
According to Maxio, gross MRR churn is calculated by dividing churned MRR plus contraction MRR by the starting MRR for the period. That figure tells you how much revenue you lost. It says nothing about how much you replaced. Only by pulling churn out of the blended growth number can you see which company you actually run.
Expansion Revenue as a Churn Mask
Upsells and expansion revenue make this problem worse, not better, when they are not examined closely. A business can have both an accelerating churn rate and rising MRR at the same time, as long as a shrinking pool of remaining customers is spending more.
Say a company starts the quarter with 500 customers and $500,000 in MRR. Ten percent of those customers, worth $60,000, cancel. But the remaining 450 customers get upsold to premium tiers, adding $75,000 in expansion revenue. Net MRR still grew by $15,000. Meanwhile, the company just lost 10% of its logos.
That is a real pattern, not a hypothetical one. It shows up most in vertical SaaS and tools sold to power users, where the customers who stay are enthusiastic enough to pay more, while the customers who never got value simply leave. Expansion revenue from the remaining base can offset logo churn for several quarters before the shrinking customer count catches up with total revenue.
The fix is to look at logo churn and revenue churn side by side, not one or the other. A company with flat or growing revenue but a falling customer count is trading breadth for depth, and depth has a ceiling.
NRR vs MRR: Why Investors Stopped Trusting Growth-Only Numbers
Net revenue retention exists precisely to separate these two effects. According to Arbutus Management Consulting, NRR is calculated by taking starting MRR, adding expansion, subtracting contraction and churn, then dividing by that same starting MRR. Critically, it excludes new customer revenue entirely.
That exclusion is the whole point. NRR answers one question: if you stopped selling to new customers today, would your existing base still grow revenue on its own? According to Arbutus, an NRR above 100% means the answer is yes, and that signals durable product value that does not depend on the sales team working harder every quarter.
There is also a clean mathematical link between NRR and net MRR churn. According to MetricHQ, NRR equals 100% minus the net MRR churn rate, so an NRR of 110% is mathematically the same as a negative 10% net churn rate. When you hear a SaaS company boast about "negative churn," this is what they mean: expansion revenue from existing accounts is outpacing everything they lose to cancellations and downgrades combined.
According to Arbutus, this is also why NRR has become the most closely watched SaaS metric among investors. It strips out the noise of a hot sales quarter and shows whether the underlying product keeps customers, and grows with them, on its own merits.
The stakes are not academic. According to Getmonetizely, public SaaS companies with NRR above 120% trade at valuation multiples roughly 25% higher than companies with NRR below 100%. The same top-line growth rate can support very different valuations depending on where that growth actually comes from.
Q: Can a SaaS company have strong MRR growth while experiencing high churn?A: Yes. As long as new sales or expansion revenue outpace what is lost to cancellations and downgrades, the net MRR number can rise even while a large share of the existing customer base leaves each period.
Q: What is the difference between gross and net MRR churn?A: Gross churn measures revenue lost from cancellations and downgrades against starting MRR, with no offset. Net churn subtracts that lost revenue but adds back expansion revenue from the surviving customers, which is why net churn can look far healthier than gross churn.
The Cohort Blind Spot
Aggregate MRR numbers blend together customers who signed up in January with customers who signed up eighteen months ago. That blending hides a common failure pattern: churn accelerating inside a specific cohort while the company-wide number stays flat.
A cohort analysis groups customers by signup month and tracks what percentage of their original revenue survives over time. If the cohort that joined a year ago is down to 60% of its starting revenue, but new cohorts keep replacing that lost volume, the blended MRR chart shows smooth growth right up until the pipeline of new customers runs thin.
A simple way to run this check:- Group customers by the month they became paying subscribers.
- Track each cohort's remaining MRR at months 3, 6, 12, and 18.
- Compare the retention curve of your most recent three cohorts against your oldest three.
- If newer cohorts are retaining worse than older ones, your product-market fit or onboarding is degrading, even if total MRR looks fine.
This is where the lag in the MRR churn relationship becomes dangerous. Churn acceleration inside a cohort can take a year or more to show up as a company-wide problem, because new sales are still masking it. By the time the blended number turns down, the underlying cause is often months old.
Acquisition Quality and the MRR-Churn Trap
Not all new MRR is equal, and the acquisition channel matters more than most growth dashboards admit. A sales team under pressure to hit quota will sometimes close customers who are a poor fit for the product, just to book the number.
Those customers inflate MRR the day they sign. They also tend to churn faster, because they never had the underlying need the product solves. A SaaS company that increases spend on broad, low-intent channels can post record new MRR one quarter and record churn the next, from the same cohort of buyers.
This is one reason CAC payback period and churn rate move together in practice. If it takes 18 months to recoup the cost of acquiring a customer, but that customer churns in month 10, the company never recovers its acquisition spend. According to common SaaS benchmarking guidance, CAC payback should stay under 12 months, and pairing that target with churn data tells you whether your growth spend is actually profitable.
| Signal | What it means |
|---|---|
| High MRR, rising churn | New sales masking customer loss |
| High MRR, stable churn | Genuine, durable growth |
| Flat MRR, falling churn | Retention improving, sales lagging |
| Falling MRR, rising churn | Structural product or fit problem |
This table shows how the direction of MRR and churn together, not MRR alone, indicates business health.
Early Warning Signs Before MRR Turns Down
Waiting for total MRR to decline is the slowest possible way to notice a churn problem. By the time it shows up there, the damage has been compounding for quarters. A few earlier signals are worth tracking on a monthly cadence:
- Logo churn rising while revenue churn stays flat. This means you are losing more customers, but expansion from survivors is covering it. That cannot continue indefinitely.
- Support ticket volume or sentiment worsening in a specific segment. Product complaints often precede cancellation by months.
- Usage frequency dropping in the weeks before renewal. A customer who logs in less is a customer close to leaving.
- New cohort retention curves flattening compared to older cohorts. This flags an onboarding or fit problem before it hits the aggregate number.
- NRR trending down even slightly quarter over quarter. According to Arbutus, an NRR drifting from 110% toward 100%, or below, is an early signal worth acting on immediately, not waiting out.
According to Arbutus, an NRR below 90% should raise real concern and prompt a direct look at retention and product-market fit. Watching for the drift toward that line is far more useful than waiting to cross it.
Benchmarking Against Reality
It helps to know where typical performance actually sits, so a founder can judge their own numbers against something other than the loudest growth story on social media. According to Meerako, the median B2B SaaS company runs a 3.5% annual churn rate, a 3.4 LTV to CAC ratio, and 101% net revenue retention.
That median NRR of 101% is barely positive. It means the typical SaaS business is close to flat once new sales are excluded, not the negative-churn juggernaut often implied by growth headlines. According to Meerako, the gap between median performers and top-quartile performers on churn, LTV to CAC, and NRR has been widening every year, which means mediocre retention is getting more costly relative to the best operators, not less.
Building Sustainable Growth
Balancing MRR expansion against retention is not about choosing one metric to optimize. According to FinModelBuilder, weakness in any single metric, whether it is MRR growth, churn, CAC payback, LTV to CAC, or NRR, tends to drag down the others over time because they are part of one interconnected system.
Practical priorities for a founder looking at their own dashboard:
- Report gross and net churn separately every month. Never let expansion revenue net against logo loss without seeing both numbers.
- Track NRR as a primary metric, not a footnote. Aim for the 100 to 110% range that Arbutus identifies as healthy, and treat drift below that as urgent.
- Run cohort retention curves quarterly. Compare new cohorts to old ones to catch onboarding or fit problems early.
- Pair CAC payback with churn data. A payback period under 12 months, matched with an LTV to CAC ratio above 3 to 1, is the combination that supports durable unit economics.
- Segment growth by acquisition channel. If one channel drives cheap new MRR but feeds disproportionate churn, that channel is not actually cheap.
The Bottom Line
MRR growth answers one narrow question: is more money coming in than last month. It does not answer whether the customers behind that money are staying, growing, or quietly heading for the exit. A founder who only watches the top line can run a business that looks strong in board decks and is structurally weak underneath.
The fix does not require abandoning MRR as a metric. It requires refusing to look at it alone. Track gross churn, net churn, NRR, and cohort retention side by side with growth, and treat any divergence between them as the earliest signal you will get that something under the hood needs attention.
Sources
Researched from the following. Figures and claims were current when this piece was written and may have moved since.
- Arbutus Management Consultingarbutusmc.com
- Maxiomaxio.com
- MetricHQmetrichq.org
- Ekolsoftekolsoft.com
- Getmonetizelygetmonetizely.com
- FinModelBuilderfinmodelbuilder.com